Making Medicare Preventive Care Work for Your Loved One

By Roz Jones

Preventive care only works when it becomes part of the regular care plan. Medicare covers a wide range of preventive services, but coverage alone does not guarantee that every screening, vaccine, or wellness visit will happen when it should. Caregivers often become the person helping an aging loved one keep track of what has been completed, what is overdue, and what needs to be discussed at the next appointment.

That coordination matters because preventive care is not just about checking boxes. It is about identifying changes early enough to respond before they become larger health concerns. Medicare continues to cover preventive services that include screenings, vaccines, counseling, and wellness visits designed to help detect health risks and support ongoing health.

Make the Wellness Visit More Useful

The yearly Medicare Wellness Visit can be an important part of preventive care, but it is often misunderstood. It is not the same as a routine physical exam. The purpose of the visit is to review health risks, medications, medical and family history, and create or update a personalized prevention plan. Medicare also includes a cognitive assessment as part of the visit and may provide a written schedule for screenings and other preventive services that should be considered.

Caregivers can make these visits more useful by helping an aging loved one arrive prepared. An updated medication list, recent health changes, family history, and notes about new concerns can help the provider see the larger picture. The visit can also be a good time to ask what preventive services are due and whether any previous screenings need to be repeated.

The same preparation applies to the one-time “Welcome to Medicare” preventive visit during the first 12 months of Part B coverage. That visit can include a review of medical history, risk factors, medications, vaccinations, and recommended preventive services. It is another opportunity to build a stronger health plan before problems become more difficult to manage.

Know the Difference Between Preventive and Diagnostic Care

One of the most important things caregivers can understand is that a preventive service may not always remain preventive.

A screening is generally performed when there are no symptoms and the goal is early detection. Once there is a symptom, abnormal result, or known health concern, additional testing may be considered diagnostic instead. That distinction can affect what Medicare pays and what the patient may owe.

This can also happen during a Wellness Visit. Medicare states that the preventive visit may have no cost when the provider accepts assignment, but additional tests or services performed during the same appointment may involve coinsurance or the Part B deductible if they are outside the preventive benefit.

Caregivers should not avoid needed testing because of cost concerns, but it is reasonable to ask how a service will be billed and what Medicare is expected to cover. Knowing the difference before an appointment can help reduce unexpected charges and make healthcare planning easier.

Keep Preventive Care Connected to Current Health Needs

Preventive care should change as an aging loved one’s health changes. A screening schedule that made sense several years ago may need to be reconsidered after a new diagnosis, medication change, hospitalization, or change in mobility.

The yearly Wellness Visit can help bring those changes together. Medicare allows providers to review current prescriptions, discuss health risks, assess cognitive function, and update the prevention plan based on the person’s current health. A physical activity and nutrition risk assessment may also be included during the visit, helping providers understand how daily habits may be affecting overall health.

Caregivers can support that process by keeping records current instead of relying on memory at the appointment. Knowing when the last screening occurred, what the results were, and whether a follow-up was recommended can make the next healthcare conversation much more productive.

Pay Attention to Mental and Cognitive Health

Preventive care should not focus only on physical health. Medicare continues to cover depression screening under certain conditions, and the yearly Wellness Visit includes an assessment for possible cognitive impairment. If a provider identifies concerns, Medicare may also cover a separate cognitive assessment visit for a more detailed review and care planning.

These conversations can be especially important for caregivers who have noticed subtle changes at home. Difficulty managing finances, remembering instructions, keeping appointments, or making everyday decisions may be worth discussing with the healthcare provider.

Early attention does not automatically mean a serious diagnosis is present. It creates an opportunity to understand what is changing and determine whether additional evaluation or support is needed.

Use the Prevention Plan Throughout the Year

Preventive care should not begin and end with one appointment. The plan created during a Wellness Visit can help caregivers stay aware of what needs to happen throughout the year.

That may mean scheduling a screening several months later, checking whether a vaccine is due, or following up on a recommendation that was made during the visit. Medicare also allows beneficiaries to review preventive services through their secure Medicare account, which can help families stay organized between appointments.

A simple healthcare record can also help. Keeping appointment dates, completed screenings, vaccinations, medication changes, and follow-up recommendations in one place reduces the chance that something important will be missed.

Prevention Works Best When the Care Plan Stays Current

Preventive services are valuable because they create opportunities to find health concerns earlier, but they are most effective when they are connected to the care already happening. A caregiver who understands the loved one’s current medications, diagnoses, recent changes, and healthcare priorities is better prepared to help make those services meaningful.

The goal is not to schedule every possible screening simply because Medicare offers it. The goal is to work with the healthcare provider to understand which preventive services are appropriate for the aging loved one now.

That approach keeps preventive care focused on the person instead of the calendar.

If you have not read the first blog in this series, start with The Power of Preventive Services in Medicare. It provides an introduction to the preventive services Medicare offers and how those benefits can support an aging loved one’s health.

Tune in to The Caregiver Café Podcast

9 Things to Consider After Hospital Discharge
Listen to The Caregiver Cafe Podcast: 9 Things to Consider After Hospital Discharge for guidance on preparing for the transition home and the responsibilities that may follow a hospital stay.

Give Yourself a Moment of Grace
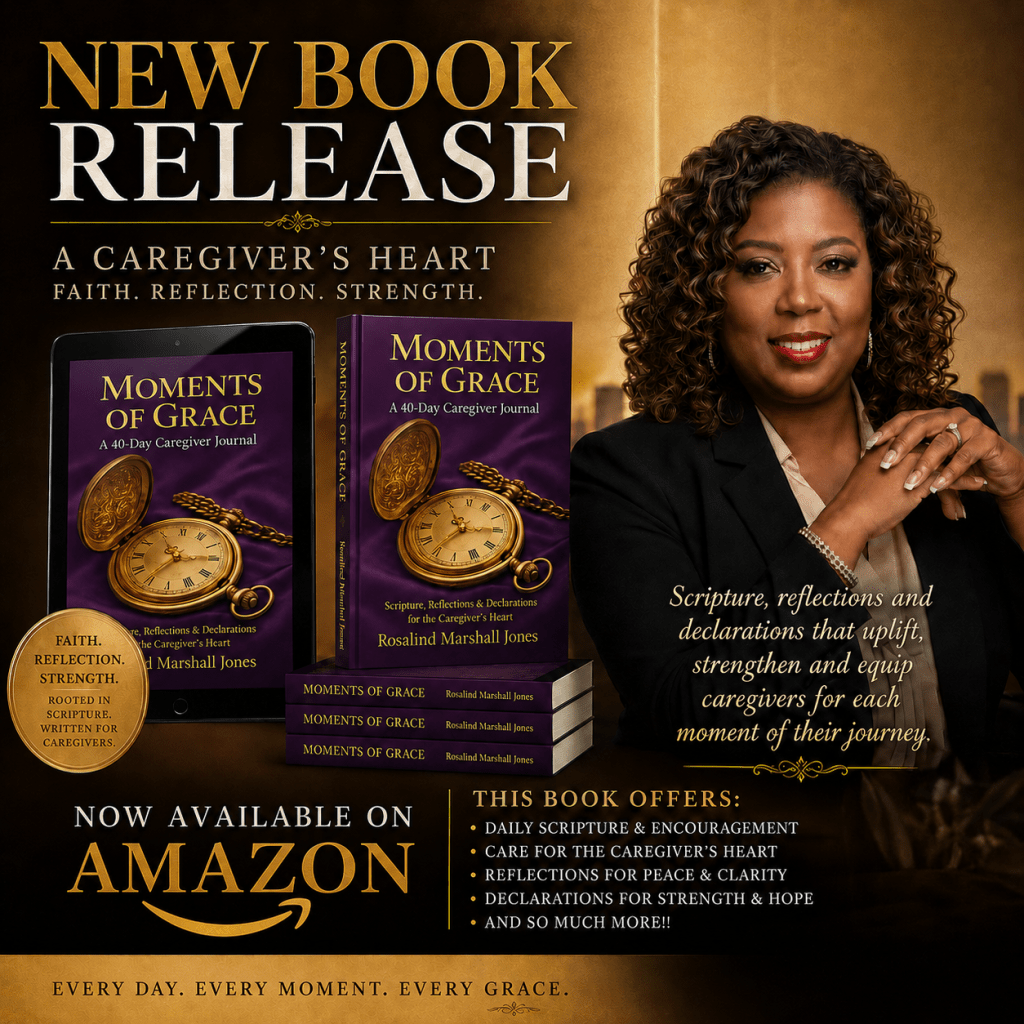
Caregiving includes demanding days, unexpected changes, and moments of connection that may be easy to overlook. Moments of Grace offers encouragement to caregivers who need a reminder to pause and recognize the meaningful moments along the journey.

Preparing for hurricane season?
The Caregiver Hurricane Preparedness Checklist.

Are you preparing for hurricane season? Purchase the Caregiver Hurricane Preparedness Checklist to organize the information and supplies your family may need before severe weather arrives.

Subscribe to The Caregiver Cafe Weekly Newsletter!
Caregiving can be a roller coaster of ups and downs. The information that you will receive from The Caregiver Cafe Weekly Specials Newsletter will support you as a caregiver. Remember…

1. YOU ARE NOT ALONE: The problems you face as a caregiver are experienced by other caregivers. Knowing that you’re not alone can be comforting. 

2. Tools and Resources:  Find caregiver stress management tools and gain perspective from other caregiver’s experiences.

3. LEARN TO: Ask for help, accept help when it is offered, and acknowledge yourself on this caregiving journey. Hear from experts on how to balance caregiving responsibilities by taking care of your needs and involving others to help manage the natural stress and isolation of being a caregiver. 
Research Medicare Before the Deadline Finds You

By Roz Jones

Understanding Medicare is one thing. Sitting down to compare coverage for an aging loved one is another.

Families can quickly find themselves surrounded by plan information, insurance mailers, prescription lists, provider directories, premium amounts, and healthcare terminology. Research becomes easier when the focus shifts from trying to understand every available option to understanding what an aging loved one actually needs from their coverage.

For family caregivers, the goal is not to memorize Medicare. It is to gather the information needed to recognize whether current coverage still supports the healthcare an aging loved one is receiving.

Start With the Care Already Being Used

Medicare research should begin with an aging loved one’s actual healthcare routine.

Current physicians, specialists, medications, recurring treatments, medical equipment, and expected follow-up care provide a clearer starting point than advertisements for individual plans. These are the services that coverage needs to support.

Changes during the year also matter. A new diagnosis, additional medication, recent hospitalization, or increase in specialist visits can make last year’s healthcare needs look very different from this year’s.

Review What Changed Before Comparing Plans

Insurance coverage can change from one year to the next, even when an aging loved one stays enrolled in the same plan.

Premiums, prescription costs, provider participation, benefits, and other coverage details may change. Reviewing notices from the current plan can help caregivers identify those differences before comparing other options.

This is also an opportunity to look at what worked during the year. Frequent billing problems, difficulty accessing providers, unexpected prescription expenses, or services that became harder to obtain may deserve closer attention during the next review.

Look Beyond the Monthly Premium

A lower monthly premium does not always mean lower healthcare costs.

An aging loved one may still be responsible for copayments, coinsurance, deductibles, medications, and other expenses when healthcare services are used. Comparing only the monthly premium can leave families with an incomplete picture of what coverage may actually cost throughout the year.

The better comparison is how the coverage works alongside the healthcare an aging loved one regularly receives.

Check Medications Carefully

Prescription needs can play a major role in Medicare plan selection.

A medication that was affordable under one plan may have a different cost under another. Coverage can also change when medications are added, discontinued, or replaced during the year.

Keeping an updated medication list gives caregivers something concrete to use during plan research. The medication name, dosage, frequency, and preferred pharmacy can all become important when comparing prescription coverage.

Confirm Access to Current Providers

Continuity of care can be especially important for an aging loved one managing ongoing health conditions.

A physician who has treated someone for years may understand their medical history, previous treatments, and personal preferences in a way that cannot easily be replaced.

Provider access should therefore be part of the research process. Families should understand how a potential change in coverage may affect the doctors, specialists, hospitals, and other healthcare professionals already involved in the care plan.

Keep Research Organized

Medicare research becomes harder when information is scattered across multiple websites, handwritten notes, mailers, and phone conversations.

Keeping the information together can make comparisons easier. Notes from insurance calls, current medications, provider information, coverage documents, and questions that still need answers can become part of the same healthcare file used throughout the year.

Organization also makes it easier to return to the research without starting over each time.

Give Research Enough Time

Waiting until a deadline is approaching can turn healthcare research into a rushed decision.

Caregivers are already managing appointments, medications, transportation, work, family responsibilities, and the daily needs of an aging loved one. Medicare research often has to fit around everything else.

Beginning early creates room to compare information, ask questions, confirm details, and revisit something that does not make sense. A thoughtful decision is much easier to make when the family is not trying to complete the entire process at the last minute.

Make the Research Part of Care Planning

Medicare coverage affects more than an insurance card.

It can influence access to physicians, prescription expenses, hospital care, follow-up services, and the amount of healthcare spending a family needs to prepare for.

That makes Medicare research part of the larger caregiving plan.

As an aging loved one’s healthcare needs change, the questions being asked about coverage may need to change too. Reviewing those needs regularly can help families recognize when current coverage continues to work and when it may be time to research other options.

The earlier blog, The Medicare Maze: How to Conduct Effective Research for Plan Selection, provides the foundation for understanding the different parts of Medicare and why reviewing coverage matters. This continuation takes that information into the caregiving process by focusing on what families can examine when researching whether a loved one’s coverage still fits their needs.

Prepare for Your Next Trip

Planning to travel with an aging loved one? Download the free Vacationing with an Aging Loved One Checklist to help you prepare for medications, mobility needs, comfort, safety, and unexpected changes.

Tune in to The Caregiver Café Podcast

How to avoid hospital re-admission for your loved ones

The transition home after a hospitalization can include medication changes, follow-up appointments, new care instructions, and additional responsibilities for the family caregiver. How those changes are managed can have an important impact on recovery.

Listen to the latest episode of The Caregiver Cafe, “How to Avoid Hospital Re-Admission for Your Loved Ones,” for practical information on preparing for the transition home and supporting an aging loved one after discharge.

Give Yourself a Moment of Grace

Caregiving includes demanding days, unexpected changes, and moments of connection that may be easy to overlook. Moments of Grace offers encouragement to caregivers who need a reminder to pause and recognize the meaningful moments along the journey.

Preparing for hurricane season?

The Caregiver Hurricane Preparedness Checklist.

Are you preparing for hurricane season? Purchase the Caregiver Hurricane Preparedness Checklist to organize the information and supplies your family may need before severe weather arrives.

Subscribe to The Caregiver Cafe Weekly Newsletter!

Caregiving can be a roller coaster of ups and downs. The information that you will receive from The Caregiver Cafe Weekly Specials Newsletter will support you as a caregiver. Remember…

1. YOU ARE NOT ALONE: The problems you face as a caregiver are experienced by other caregivers. Knowing that you’re not alone can be comforting. 

2. Tools and Resources:  Find caregiver stress management tools and gain perspective from other caregiver’s experiences.

3. LEARN TO: Ask for help, accept help when it is offered, and acknowledge yourself on this caregiving journey. Hear from experts on how to balance caregiving responsibilities by taking care of your needs and involving others to help manage the natural stress and isolation of being a caregiver. 

Keeping Your Loved One’s Medicare Coverage Aligned With Changing Care

By Roz Jones

Choosing Medicare coverage is not the end of the planning process. An aging loved one’s health, medications, providers, and level of support can change over time, and those changes can affect how well existing healthcare coverage continues to meet their needs.

A plan that made sense when an aging loved one first enrolled in Medicare may continue to work for years. Still, healthcare coverage should remain part of the larger care plan rather than becoming something the family chooses once and never reviews again.

Watch How Healthcare Needs Change

Healthcare needs often change gradually. An aging loved one may begin seeing physicians more frequently, managing additional health conditions, working with new specialists, or using services that were not part of their care before.

These changes do not automatically mean new coverage is necessary, but they can signal that it is time to review how existing coverage is being used. Changes in the frequency of medical care, recurring expenses, and the amount of support required can help families recognize when the healthcare picture has shifted.

Keep Coverage Information Current

Medicare information should be organized alongside the other documents used to manage care. Insurance cards, policy information, prescription coverage, medication lists, provider contacts, and important healthcare records should be easy to locate and updated when something changes.

Accurate records are especially important during hospital stays, emergency situations, and transitions in care. They also make it easier for another trusted family member or caregiver to step in when additional support is needed.

Review the Full Healthcare Budget

Healthcare expenses can change even when insurance coverage remains the same. Premiums may increase, prescriptions may change, and an aging loved one may begin using more medical services, transportation, equipment, or caregiving support.

Reviewing these expenses as part of the larger household budget can help families understand how healthcare costs are affecting the care plan. Medicare coverage is only one piece of a financial picture that may also include housing, food, medications, transportation, and daily caregiving needs.

Revisit the Plan After Major Health Changes

A hospitalization, surgery, new diagnosis, or significant change in mobility can quickly alter the amount and type of care an aging loved one needs. New medications, follow-up appointments, rehabilitation, medical equipment, or additional services may become part of the routine.

Major health changes create a natural opportunity to review the healthcare plan. Understanding what has changed and updating medical and insurance information can make the transition into a new level of care easier to manage.

Make Coverage Reviews Part of Care Planning

Care plans evolve as an aging loved one’s needs change. Families may already revisit medications, transportation, home safety, emergency contacts, and assistance with daily activities. Healthcare coverage deserves a place in that same process.

Periodic reviews can help families identify questions before an urgent situation occurs. They can also reveal whether healthcare expenses, providers, or services have changed enough to require closer attention.

Keep Your Aging Loved One Involved

Needing more assistance does not automatically remove an aging loved one from decisions about their healthcare. Whenever possible, their priorities should remain part of conversations about medical care, insurance, expenses, and changes to the overall care plan.

Those priorities may change over time. Access to familiar physicians may become more important, predictable healthcare expenses may become a greater concern, or receiving care closer to home may become a priority. Including those preferences helps keep the care plan centered on the person receiving the care.

Participation, not isolation, remains important throughout the caregiving journey.

Prepare Before Care Changes Again

Caregiving rarely remains the same for long. Organized healthcare information gives families a stronger starting point when the next change occurs.

Knowing what coverage is in place, where important documents are stored, which medications and providers are current, and who to contact with questions can reduce confusion during an already stressful transition. Preparation cannot eliminate difficult healthcare decisions, but it can make those decisions easier to manage.

If you have not read the first part of this blog, start with Your Roadmap to Medicare Supplemental Insurance. That article focuses on evaluating Medigap plans, comparing costs, considering enrollment timing, and making informed decisions about supplemental coverage.

Prepare for Your Next Trip

Planning to travel with an aging loved one? Download the free Vacationing with an Aging Loved One Checklist to help you prepare for medications, mobility needs, comfort, safety, and unexpected changes.

Tune in to The Caregiver Café Podcast

How to avoid hospital re-admission for your loved ones

The transition home after a hospitalization can include medication changes, follow-up appointments, new care instructions, and additional responsibilities for the family caregiver. How those changes are managed can have an important impact on recovery.

Listen to the latest episode of The Caregiver Cafe, “How to Avoid Hospital Re-Admission for Your Loved Ones,” for practical information on preparing for the transition home and supporting an aging loved one after discharge.

Give Yourself a Moment of Grace

Caregiving includes demanding days, unexpected changes, and moments of connection that may be easy to overlook. Moments of Grace offers encouragement to caregivers who need a reminder to pause and recognize the meaningful moments along the journey.

Preparing for hurricane season?

The Caregiver Hurricane Preparedness Checklist.

Are you preparing for hurricane season? Purchase the Caregiver Hurricane Preparedness Checklist to organize the information and supplies your family may need before severe weather arrives.

Subscribe to The Caregiver Cafe Weekly Newsletter!

Caregiving can be a roller coaster of ups and downs. The information that you will receive from The Caregiver Cafe Weekly Specials Newsletter will support you as a caregiver. Remember…

1. YOU ARE NOT ALONE: The problems you face as a caregiver are experienced by other caregivers. Knowing that you’re not alone can be comforting. 

2. Tools and Resources:  Find caregiver stress management tools and gain perspective from other caregiver’s experiences.

3. LEARN TO: Ask for help, accept help when it is offered, and acknowledge yourself on this caregiving journey. Hear from experts on how to balance caregiving responsibilities by taking care of your needs and involving others to help manage the natural stress and isolation of being a caregiver. 
When Medicare Coverage Becomes Part of Caregiving

By Roz Jones

Choosing Medicare coverage is only one part of the process. Once Original Medicare, supplemental insurance, and prescription coverage are in place, caregivers are often left managing the paperwork, billing questions, hospital transitions, and follow-up care that come with using that coverage.

That responsibility can become part of the larger caregiving routine. Insurance cards need to be accessible, medical bills need to be reviewed, changes in medication may affect prescription coverage, and hospital stays can introduce new providers, services, and expenses. Keeping those details organized can make it easier to respond when care needs change.

Keep Important Healthcare Information Together

Insurance information should be stored with the other documents used to manage an aging loved one’s care. Medicare cards, supplemental insurance information, prescription coverage, medication lists, provider contacts, and recent medical records are easier to manage when they are kept in one location.

This becomes especially important during an emergency or hospitalization. Searching for documents during a crisis creates additional stress at a time when the focus needs to remain on the aging loved one’s care.

Keeping information updated also matters. Changes in providers, medications, coverage, or contact information should be reflected in the records caregivers rely on.

Review Medical Paperwork Carefully

Medical care can generate a steady stream of paperwork. Bills, Medicare statements, insurance notices, pharmacy receipts, hospital discharge documents, and provider statements can all arrive within a short period of time.

Not every document requires payment, and not every charge should be handled before insurance finishes processing the claim. Reviewing paperwork carefully can help caregivers understand what was billed, what insurance paid, and what amount may actually remain.

When information does not match or a charge is unclear, contacting the provider or insurance company can help resolve the issue before an unnecessary payment is made.

Keep a Record of Insurance Calls

Caregivers may need to contact Medicare, a supplemental insurer, a prescription plan, or a healthcare provider more than once about the same issue.

Keeping brief notes from those conversations can make follow-up easier. The date of the call, the name of the representative, the reason for the call, and any confirmation or reference number can provide useful documentation if the issue is not resolved immediately.

Those notes can also reduce the amount of information that has to be reconstructed later.

Prepare for Changes After a Hospital Stay

A hospital discharge can quickly create new caregiving responsibilities. Medications may change, follow-up appointments may be added, new equipment may be needed, or temporary home health services may become part of the care plan.

Insurance questions often surface during this transition because different services may be billed separately or handled by different providers.

Caregivers should review discharge paperwork closely and make sure they understand what services are being recommended, what follow-up care is required, and who should be contacted when questions arise.

Pay Attention During the First Weeks at Home

The transition home is often when caregivers begin to see whether the care plan is working.

An aging loved one may need more assistance than expected. A medication may cause side effects. Mobility may be different. Follow-up appointments may be difficult to coordinate. New symptoms may also appear.

Those changes can affect both the care plan and the services being used. Paying close attention during this period can help caregivers identify problems early and follow up before they lead to another emergency.

Keep the Aging Loved One Involved

Managing insurance and healthcare paperwork does not mean the aging loved one should automatically be removed from the decision-making process.

When possible, caregivers should continue including them in conversations about appointments, medical expenses, coverage changes, and care decisions. Staying involved can help preserve independence and make healthcare decisions feel less like something that is simply happening around them.

Participation remains an important part of caregiving, even when more support is needed.

Make Insurance Organization Part of the Care Plan

Insurance should not be treated as a separate issue from caregiving. It connects directly to medications, hospital stays, medical appointments, follow-up care, and the financial responsibilities that come with supporting an aging loved one.

Keeping healthcare information organized can make those responsibilities easier to manage and reduce unnecessary confusion when something changes.

If you have not read the first part of this series, start with The Pros and Cons of Medicare Supplemental Insurance for Aging Loved Ones. That article breaks down the advantages and potential drawbacks of Medigap coverage and provides the foundation for understanding how supplemental insurance can fit into an aging loved one’s healthcare plan.

Prepare for Your Next Trip

Planning to travel with an aging loved one? Download the free Vacationing with an Aging Loved One Checklist to help you prepare for medications, mobility needs, comfort, safety, and unexpected changes.

Tune in to The Caregiver Café Podcast

How to avoid hospital re-admission for your loved ones

Hospital discharge is only one part of recovery.

The days that follow can determine whether an aging loved one continues to improve or ends up needing additional care. Medication changes, missed follow-up appointments, and confusion about discharge instructions can all create complications.

Listen to the latest episode of The Caregiver Cafe, “How to Avoid Hospital Re-Admission for Your Loved Ones,” for practical information on preparing for a safer transition home.

Give Yourself a Moment of Grace

Caregiving includes demanding days, unexpected changes, and moments of connection that may be easy to overlook. Moments of Grace offers encouragement to caregivers who need a reminder to pause and recognize the meaningful moments along the journey.

Preparing for hurricane season?

The Caregiver Hurricane Preparedness Checklist.

Are you preparing for hurricane season? Purchase the Caregiver Hurricane Preparedness Checklist to organize the information and supplies your family may need before severe weather arrives.

Subscribe to The Caregiver Cafe Weekly Newsletter!

Caregiving can be a roller coaster of ups and downs. The information that you will receive from The Caregiver Cafe Weekly Specials Newsletter will support you as a caregiver. Remember…

1. YOU ARE NOT ALONE: The problems you face as a caregiver are experienced by other caregivers. Knowing that you’re not alone can be comforting. 

2. Tools and Resources:  Find caregiver stress management tools and gain perspective from other caregiver’s experiences.

3. LEARN TO: Ask for help, accept help when it is offered, and acknowledge yourself on this caregiving journey. Hear from experts on how to balance caregiving responsibilities by taking care of your needs and involving others to help manage the natural stress and isolation of being a caregiver. 
What Caregivers Need to Know About Medigap in 2026

By Roz Jones

Medicare decisions can become another responsibility caregivers are expected to understand, especially when an aging loved one starts receiving more healthcare. You may be helping review medical bills, keeping track of appointments, checking insurance statements, or trying to understand why Medicare paid one portion of a bill while your loved one is responsible for another. That is often when Medicare Supplement Insurance, also called Medigap, becomes part of the conversation.

Medigap can help with some of the out-of-pocket costs that remain after Original Medicare pays its share, but it is not a replacement for Medicare and it does not cover every healthcare expense your loved one may have. Understanding how the coverage works can help families decide whether it fits into the larger healthcare and financial plan.

Understand What Medigap Actually Supplements

Medigap works alongside Original Medicare, Part A and Part B. Medicare pays its share of covered healthcare costs first, and the Medigap policy may then pay some or all of the remaining costs covered under that particular policy.

Those remaining costs can include deductibles, coinsurance, and copayments. Without supplemental coverage, those expenses can become difficult to predict, especially for an aging loved one who sees several providers, receives outpatient services regularly, or experiences a hospitalization.

One important distinction for caregivers to understand is that Medigap is not the same thing as Medicare Advantage. Medicare Advantage is another way to receive Medicare benefits, while Medigap supplements Original Medicare. Your loved one cannot use a Medigap policy to pay the copayments, deductibles, or premiums associated with a Medicare Advantage plan.

Know What Medigap Does Not Cover

Having supplemental insurance does not mean every healthcare-related expense will be covered. Medigap policies generally do not cover long-term care, routine dental or vision care, hearing aids, eyeglasses, or private-duty nursing.

Prescription drug coverage is also separate. Medigap policies sold after 2005 do not include prescription drug coverage, so someone with Original Medicare and Medigap may also need a separate Medicare Part D prescription drug plan if they want drug coverage.

That distinction becomes especially important for caregivers because many of the services an aging loved one may eventually need are not automatically covered simply because they have Medicare and Medigap. If your loved one begins needing ongoing personal care at home, assistance with activities of daily living, or long-term nursing home care, Medigap should not be treated as a long-term care insurance policy.

Compare the Plan, Not Just the Insurance Company

Medigap plans are standardized in most states and identified by letters, such as Plan G, Plan K, or Plan N. That means the basic benefits of a particular lettered plan are generally the same regardless of which insurance company sells it.

The price may not be the same.

Two companies may sell the same lettered Medigap plan with the same standardized benefits and charge different premiums. Premiums can also vary based on where your loved one lives and other factors, and those premiums can increase over time.

For caregivers helping compare coverage, that means it is worth looking at more than the name of the insurance company. Compare the same plan letter across several companies and ask how premiums are determined and whether the company has a history of increasing rates. The lowest premium today may not always be the only factor worth considering when the coverage may be kept for years.

Pay Attention to When Your Loved One Enrolls

Timing matters with Medigap in a way families may not realize.

The federal Medigap Open Enrollment Period is generally a one-time six-month period that begins when someone has Medicare Part B and is age 65 or older. During that period, your loved one can generally buy any Medigap policy sold in their state regardless of health problems.

That period does not return every year like Medicare’s annual Open Enrollment Period.

After the Medigap Open Enrollment Period ends, an insurance company may be allowed to use medical underwriting when someone applies for coverage unless the person qualifies for certain guaranteed issue protections or has additional rights under state law. That can mean higher premiums, fewer options, or being denied a policy.

Caregivers should pay attention to this timeline when helping someone first transition into Medicare rather than assuming they can simply add the same supplemental coverage several years later under the same conditions.

Look at the Healthcare Your Loved One Actually Uses

Choosing coverage should begin with your loved one’s needs rather than with the plan someone else recommends.

Think about how frequently your loved one receives medical care, whether they see specialists regularly, whether they travel, what they can realistically afford each month, and how comfortable they are with unpredictable out-of-pocket expenses.

A person who rarely receives care may look at the monthly premium differently from someone managing several chronic conditions and attending frequent appointments. One family may place a higher value on predictable healthcare expenses, while another may be more focused on keeping monthly premiums manageable.

There is no single Medigap plan that is automatically right for every older adult. The goal is understanding what financial risk your loved one is trying to reduce and whether the cost of the policy makes sense within their budget.

Consider How Often Your Loved One Travels

Original Medicare generally allows someone to see any doctor or hospital in the United States that takes Medicare, which can be useful for aging loved ones who spend time in different states or travel frequently.

Some Medigap policies also provide limited coverage for emergency medical care while traveling outside the United States, which Original Medicare generally does not cover except in limited circumstances.

That does not mean a Medigap policy should automatically replace travel medical insurance. Coverage outside the United States depends on the particular Medigap plan and has limits. If your loved one travels internationally, review those benefits carefully instead of assuming all medical expenses abroad will be covered.

Remember That Plan Options Can Depend on Medicare Eligibility

Not every Medigap plan is available to every Medicare beneficiary. For example, Plans C and F are no longer available to people who became newly eligible for Medicare on or after January 1, 2020. People who were eligible for Medicare before that date may still have access to those plans depending on their circumstances.

Some states also have different rules for people under age 65 who qualify for Medicare because of disability or End-Stage Renal Disease. Federal law generally does not require insurance companies to sell Medigap policies to beneficiaries under 65, although some states provide additional protections or options.

This is another reason caregivers should avoid comparing coverage based only on what another family member or friend has. Your loved one’s eligibility, state, age, and Medicare history can affect what is actually available to them.

Understand What Your Loved One Will Still Pay

Medigap adds another monthly premium to the household budget. Your loved one still has to pay the Medicare Part B premium, and then they pay a separate premium directly to the private insurance company providing the Medigap policy.

Depending on the plan they choose, there may still be other out-of-pocket costs as well. In 2026, for example, Plans F and G may offer high-deductible versions in some states. Those policies require the beneficiary to pay Medicare-covered costs up to a $2,950 deductible in 2026 before the high-deductible Medigap policy begins paying. Plans K and L also have annual out-of-pocket limits, which are $8,000 and $4,000 respectively in 2026.

Caregivers should look at the entire cost picture instead of focusing only on the monthly premium. Consider what your loved one would pay each month, what expenses they could still face when they receive care, and whether those costs remain manageable alongside medications, housing, transportation, food, and other caregiving expenses.

Get Unbiased Help Before Making the Decision

Medicare can become confusing quickly because families are often comparing Original Medicare, Medicare Advantage, Part D prescription drug coverage, Medigap policies, employer or retiree coverage, and sometimes Medicaid at the same time.

You do not have to understand all of that by yourself.

Every state has a State Health Insurance Assistance Program, or SHIP, that provides free counseling to people with Medicare and their families. SHIP counselors are not insurance agents and are not connected to a particular insurance company or health plan. Medicare specifically recommends contacting SHIP when consumers need help comparing their options.

That can be especially useful when a caregiver wants someone to explain the differences without immediately being sold a policy.

Review Coverage as Part of the Larger Care Plan

Insurance should not be reviewed separately from everything else happening in your loved one’s life. A healthcare plan that worked when they first enrolled in Medicare may need another look as their health, finances, prescriptions, travel habits, or care needs change.

Medigap policies themselves are generally guaranteed renewable as long as premiums continue to be paid, but that does not mean families should stop paying attention to costs. Premiums may increase over time, and other parts of Medicare coverage, including prescription drug plans, may also need to be reviewed separately.

Keep insurance information with the other documents you use to manage care. Know which Medicare coverage your loved one has, which company provides the Medigap policy, how premiums are being paid, and who to contact when you have questions about a bill or claim. The more organized that information is, the easier it becomes to help when something changes.

I first talked about supplemental coverage in Unraveling the Maze of Medicare Supplemental Insurance. The basic purpose of Medigap has not changed, but caregivers in 2026 still need to understand the difference between Medigap and Medicare Advantage, how enrollment timing affects access to coverage, what supplemental policies do not pay for, and why comparing both benefits and long-term costs matters.

Prepare for Your Next Trip

Planning to travel with an aging loved one? Download the free Vacationing with an Aging Loved One Checklist to help you prepare for medications, mobility needs, comfort, safety, and unexpected changes.

Tune in to The Caregiver Café Podcast

Struggling with being patient as a Caregiver

In this episode of The Caregiver Café with Roz Jones, Roz is talking about something every caregiver has probably struggled with at one time or another: patience.

Caregiving does not happen in a perfect environment. You may wake up late, your schedule may change, something unexpected may happen with your aging loved one, or you may simply be tired, hungry, overwhelmed, and trying to get too much done at once. Before you know it, something small can push you from calm to frustrated.

And Roz will be the first to tell you—she is working on this right along with you.

In this episode, Roz breaks down six reasons we often struggle with patience, including disrupted routines, feeling like there is never enough time, comparing our progress to someone else’s, becoming overwhelmed, expecting results too quickly, and trying to function when we are tired or hungry.

Give Yourself a Moment of Grace

Caregiving includes demanding days, unexpected changes, and moments of connection that may be easy to overlook. Moments of Grace offers encouragement to caregivers who need a reminder to pause and recognize the meaningful moments along the journey.

Preparing for hurricane season?

The Caregiver Hurricane Preparedness Checklist.

Are you preparing for hurricane season? Purchase the Caregiver Hurricane Preparedness Checklist to organize the information and supplies your family may need before severe weather arrives.

Subscribe to The Caregiver Cafe Weekly Newsletter!

Caregiving can be a roller coaster of ups and downs. The information that you will receive from The Caregiver Cafe Weekly Specials Newsletter will support you as a caregiver. Remember…

1. YOU ARE NOT ALONE: The problems you face as a caregiver are experienced by other caregivers. Knowing that you’re not alone can be comforting. 

2. Tools and Resources:  Find caregiver stress management tools and gain perspective from other caregiver’s experiences.

3. LEARN TO: Ask for help, accept help when it is offered, and acknowledge yourself on this caregiving journey. Hear from experts on how to balance caregiving responsibilities by taking care of your needs and involving others to help manage the natural stress and isolation of being a caregiver.